

For most of the past five years, private credit felt like a one-way trade, after all it was “The Golden Age of Private Credit”. Direct lenders offered floating-rate income, low reported volatility, and stable NAVs. Private credit teams were the superstars of the moment and pensions, endowments, sovereign wealth funds and increasingly individuals started to allocate increasingly to private credit. But the story has now shifted. Not because private credit is broken (at least the underlying assets, in my opinion), but because the strategy is colliding with a familiar stress point which is a sell off in the sector(s) that private credit was largely originating to: software and tech. This has created the current period where PC is now under the spotlight, and every move is being examined.
To understand why software and tech sits at the center of today’s private credit anxiety, it is important to understand the deal flow of this GIC sector that went to private credit over the last 4-5 years. When banks struggled to syndicate leveraged loans, direct lenders largely absorbed a larger share of this financing, accelerating the land grab in sponsor backed deals. Private credit investment professionals loved the recurring revenues, scalable margins, and asset lite operations of these credits. This is why software has become a meaningful slice of middle-market lending. By deal count, software represents about 17% of BDC holdings, second only to commercial services, according to PitchBook. That concentration looked like conviction when underwriting assumed stable renewals, durable pricing power, and clear exit/refi paths. In 2026, the same concentration increasingly looks like a wall of maturity to an industry that is trying to find its new valuation multiple. And if default rates surge to 15% in this GICS sector, credit funds will be severely wounded with regard to performance.
Link: Marathon Asset Management CEO Software Default Rates
Allocators are certainly monitoring the situation. The catalyst isn’t that AI will kill software and tech overnight. But no doubt it will change the outcomes of many of these companies that are currently being financed by private credit. The question isn’t whether these borrowers will be able to pay debt service now or in 12 months, but what happens after the first or second loan extension and the borrower starts seeing faster feature commoditization. Competitive moats may weaken, and this same predictable revenue that lenders (and PE bros) loved, starts to fade and become less predictable. UBS estimates 25% to 35% of private credit portfolios have some degree of AI disruption exposure. Not necessarily default exposure, but business model sensitivity that can compress cushions in a credit structure. Throw in vintage risk with many of these deals done near peak software multiples post Covid and exits/refinancings are going to be more expensive with narrowed paths. The options are to amend/extend, sponsor support, restructuring, or pray Thoma Bravo buys you.
The headline talking points are warranted. Asset classes that raise money from retail investors and that have flooded fundraising initiatives for the better part of 5+ years deserve to be scrutinized. Retail investors have poured into private BDC’s, different types of funds, and public BDC’s. Liquidity and redemptions were a part of the investment intrigue. Now that is all being called into question with the gating of redemptions and the marks of credits within portfolios. Do investors really know what their underlying funds hold? I of course do. It is my job to know. And we are lucky that software spreads were so tight that our mandate across many different managers could not allocate to these tight spreads due to the return not being there. But among the vehicles I mentioned above, many that retail investors are now a part of, software was a large part of the portfolio.
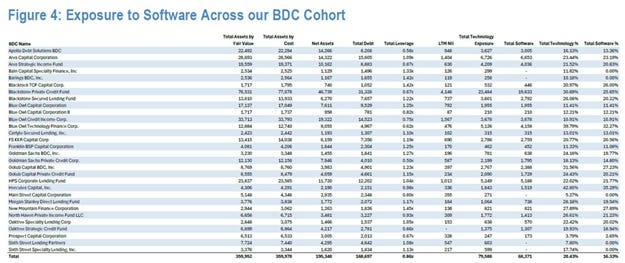
Source: JPM Research
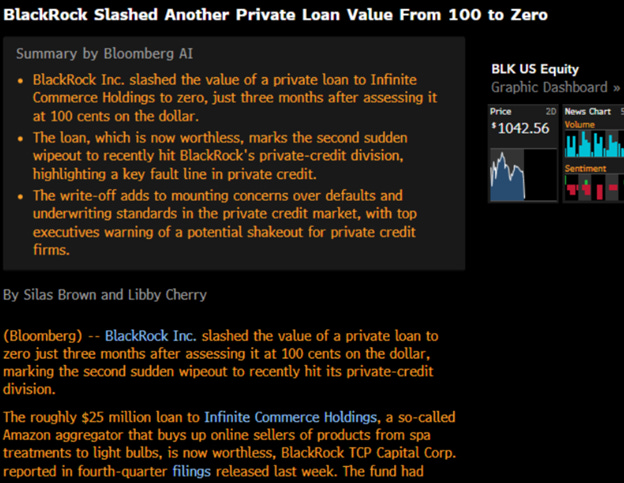
So where does that leave the institutional LPs? I am concerned about valuations and marks across investment mandates. There is clear valuation opacity. Private credit loans don’t reprice continuously like broadly syndicated loans. In benign markets, that’s a feature. In stress, it becomes a credibility test. As an allocator, I want to know the changes to loans from cash pay to PIK, and the reasons behind it. I need to know if rising PIK among borrowers is signaling cash flow problems or for legitimate growth transitions. My guess is that going from cash to PIK at this point in the credit cycle is for all the wrong reasons. Next on my mind is how these firms are prepared to operate a business that they take back during a restructuring. Obviously the higher the recovery rate (and lower the default rate), will result in material outperformance vs peers and separate top quartile managers from bottom quartile managers. One talking point not frequently mentioned is how this stress will affect regulatory oversight. Regulators are watching the growth of private markets more closely. The SEC’s FY2026 Examination Priorities explicitly call out scrutiny of complex or illiquid products, including ETFs that invest in private equity or private credit, alongside other complex/illiquid alternatives. But out of all these thoughts, I am most concerned about marks. To the many managers who read this, please kitchen sink me vs marking it down every quarter until the line item reaches its eventual grave.
One last thing. If private credit is under all this stress (according to every person on Twitter and all the negative press), what does that mean for private equity? There is a huge contrast in negative news skewed towards private credit vs private equity, but if private credit is in trouble, then so is private equity. Now keep in mind I think that the private credit headlines are overblown, but as an allocator we must respect the headlines and manage/monitor the portfolio the best we can. For PE, multiple expansion did a lot of heavy lifting for the 2010s vintages. The next few years will show which managers create operational value vs those who rode the multiple wave (and yes IRR would be helpful on the below chart since these funds are earlier in their life periods and not anywhere near their end term or asking LPs to go into the manager’s 4th continuation vehicle).
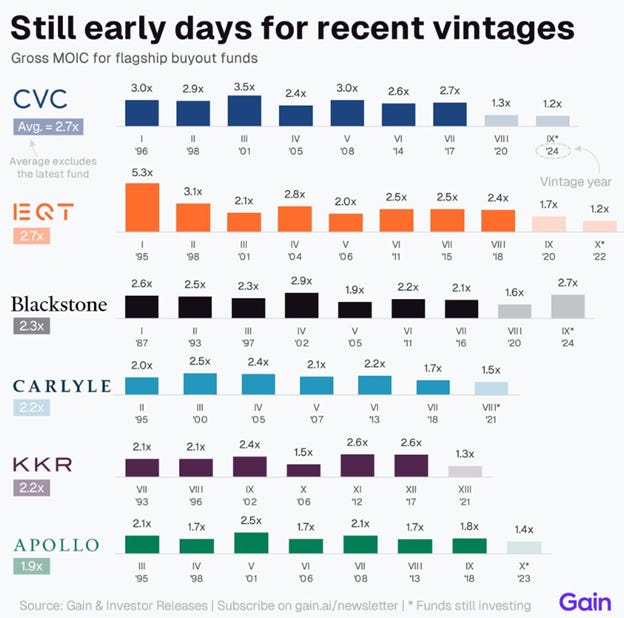
“There is a huge contrast in negative news skewed towards private credit vs private equity, but if private credit is in trouble, then so is private equity.” - i just realized that I am not hearing about PE exposure to SaaS as much)
These cycles all unfold in distinct stages over many years. The Western land boom accompanying the oil shock of the 1970s gave rise (after Garn-St. Germain regulatory easing) to the S&L development financing wave, which led to the slow motion unwind of thrifts and regional banks. It began with with Penn Square and hung on until 1989-1990 with full crisis mode and the establishment of the RTC. Same basic path for mortgage derivatives, house price mania and the eventual collapse of the whole scheme in 2008-9. Housing stocks and subprime cos. peaked 2005, but the cycle went on for another three years with greater enthusiasm and increased origination. Banks lasted 18 months even after the direction became clear during the wave of subprime mortgage company failures in 2007. In the current cycle, phase II (revaluation of the whole ecosystem) will not begin in earnest until the institutional LPs or their trustees begin to care about the accuracy of the PE marks. One major complicating factor is the inbreeding among PC fund managers and PE sponsors. Many of the outside directors of the credit funds are retired executives at the PE sponsor firms to which the PC funds are lending money. Still no incentives for anyone to play rough. Interesting that there has been no mention of auditors at any point since the valuation issues and investor concerns emerged from the shadows.